4-Point vs. Wind Mitigation Inspection in Florida: Do You Need Both?
If your Florida insurance agent tells you that you need an inspection, one of the first questions you may have is: Do I need a 4-Point Inspection, a Wind Mitigation Inspection, or both?
It’s an especially common question for homeowners in Pensacola and Northwest Florida, where insurance requirements and wind-related coverage are an important part of owning a home.
While a 4-Point Inspection and a Wind Mitigation Inspection are both commonly associated with Florida homeowners insurance, they serve very different purposes. A 4-Point Inspection documents the condition and age of four major systems in your home, while a Wind Mitigation Inspection documents features that may help your home withstand strong winds and hurricanes.
Depending on your home, insurance carrier, and situation, you may need one, the other, or both.
Here’s how to tell the difference.
What Is the Difference Between a 4-Point and Wind Mitigation Inspection?
The easiest way to understand the difference is to look at what your insurance company is trying to learn from each report.
A 4-Point Inspection focuses on four major systems:
Roof
Electrical
Plumbing
HVAC
The report gives the insurance company information about the age, type, and visible condition of these systems. This helps the carrier evaluate the home's current condition and potential insurance risk.
A Wind Mitigation Inspection looks at something different: how the home is constructed or protected against wind damage.
During a Wind Mitigation Inspection, the inspector documents features such as:
Roof covering
Roof deck attachment
Roof-to-wall connections
Roof shape or geometry
Secondary water resistance
Window, door, and garage-door opening protection
Other qualifying wind-resistant construction features
These findings are documented on Florida's Uniform Mitigation Verification Inspection Form and may qualify the homeowner for wind mitigation credits on their homeowners insurance policy.
So, while both inspections may be requested in connection with homeowners insurance, they answer two different questions:
4-Point: What condition are the home's major systems in?
Wind Mitigation: What features does the home have to help it resist wind damage?
When Do You Need a 4-Point Inspection in Florida?
A 4-Point Inspection is commonly requested by insurance carriers when they need additional information about the major systems in a home.
This is especially common with older homes, but age isn't the only reason you might be asked for one. Insurance requirements vary by carrier, property, and policy.
You may encounter a request for a 4-Point Inspection when:
Purchasing an older home
Applying for a new homeowners insurance policy
Changing insurance companies
Your current carrier requests updated information
You have made significant updates to one of the four major systems
For example, if an older 4-Point report lists an aging water heater, outdated HVAC system, older roof, or electrical condition that has since been replaced or corrected, an updated inspection can document the home's current condition.
That can be particularly important when shopping for insurance because an old report may no longer accurately represent the property.
A 4-Point Inspection does not replace a full home inspection. It is a limited inspection designed primarily to provide specific information to an insurance carrier about the roof, electrical, plumbing, and HVAC systems.
If you're purchasing a home and want a broader understanding of its condition, a full home inspection serves a different purpose.
When Do You Need a Wind Mitigation Inspection?
A Wind Mitigation Inspection isn't primarily about determining whether the major systems in your home are old or in good condition. Instead, it documents the construction features that help the home resist wind damage.
For Florida homeowners, that documentation can be particularly valuable because qualifying wind-mitigation features may result in homeowners insurance credits.
You may want or need an updated Wind Mitigation Inspection if:
You have never had one performed
Your existing Wind Mitigation report has expired
You recently replaced your roof
Hurricane clips, straps, or other roof connections were upgraded
You added secondary water resistance during a reroof
You installed qualifying impact-rated windows or doors
You added hurricane shutters
You replaced a garage door with a qualifying wind-rated product
Your insurance agent or carrier requests updated documentation
One of the biggest mistakes homeowners can make is assuming their insurance company automatically knows about improvements made to the home.
For example, replacing an older roof may change several items documented on a Wind Mitigation report. But installing the new roof does not automatically update the report already on file with your insurance company.
The same can apply to impact windows, hurricane shutters, and other improvements.
If you've made upgrades since your last Wind Mitigation Inspection, an updated report gives your insurance carrier documentation of the home's current wind-resistant features and may help you receive any additional credits for which the home qualifies.
Do You Need Both a 4-Point and Wind Mitigation Inspection?
Sometimes, yes.
Because the inspections serve different purposes, completing one does not automatically satisfy the need for the other.
A homeowner could have a newer house that doesn't require a 4-Point Inspection from their carrier but still benefit from a Wind Mitigation Inspection.
Another homeowner may be asked for a 4-Point Inspection because of the home's age but already have a current Wind Mitigation report on file.
And in many situations, particularly when purchasing or insuring an older Florida home, the insurance agent may request both.
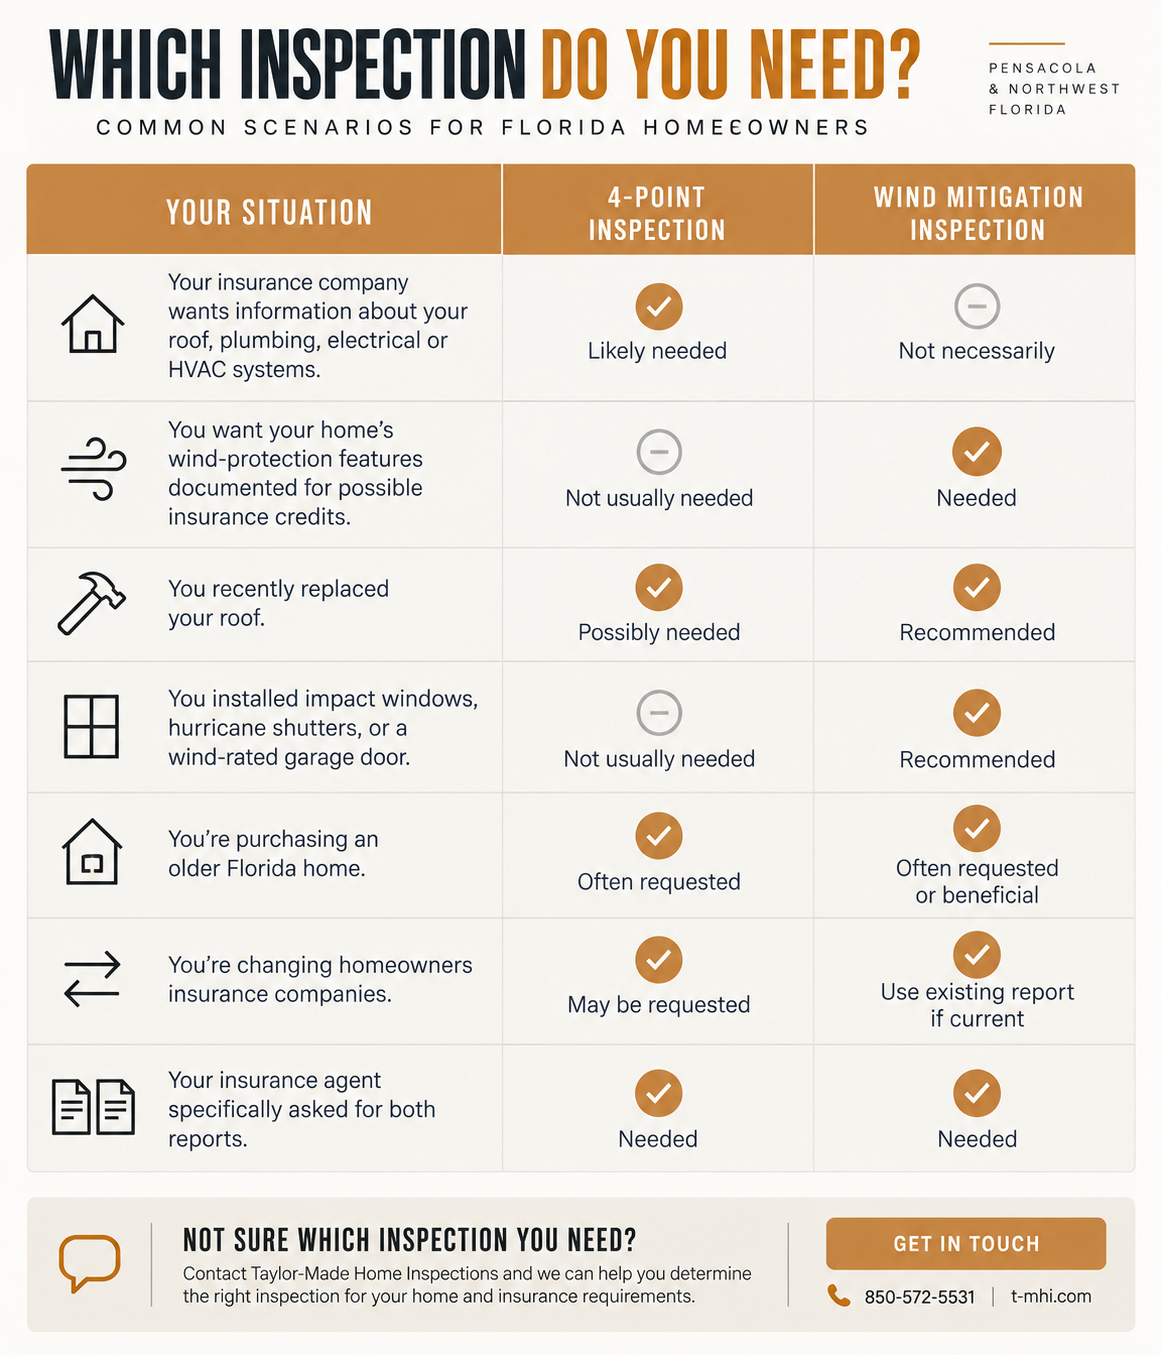
Still not sure which inspection applies to your situation? Here are a few common scenarios:
Your insurance company wants information about your roof, plumbing, electrical, or HVAC systems.
You’re most likely being asked for a 4-Point Inspection, which documents the condition and age of these four major systems.
You want your home's wind-protection features documented for possible insurance credits.
A Wind Mitigation Inspection documents features such as roof-to-wall connections, roof deck attachment, roof shape, secondary water resistance, and qualifying opening protection.
You recently replaced your roof.
Your insurance carrier may want updated information about the roof, and it may also be a good time to update your Wind Mitigation Inspection. A new roof can change several items documented on the Wind Mitigation report.
You installed impact windows, hurricane shutters, or a wind-rated garage door.
Consider updating your Wind Mitigation Inspection so those improvements can be properly documented. Simply making the upgrade doesn't necessarily mean your insurance carrier has documentation of it.
You're purchasing an older Florida home.
Your insurance carrier may request a 4-Point Inspection, and a Wind Mitigation Inspection may also be requested or beneficial. Your insurance agent can tell you exactly which reports are needed for your policy.
You're changing homeowners insurance companies.
Your new carrier may request a 4-Point Inspection or other updated documentation. If you already have a current Wind Mitigation report, ask your agent whether it can be used with the new carrier.
Your insurance agent specifically asked for both.
You need both a 4-Point and Wind Mitigation Inspection, but they can typically be completed during the same appointment.
Ultimately, your insurance carrier or agent determines which reports are required for your policy.
If you're unsure, ask exactly which inspection or form they need before scheduling. At Taylor-Made Home Inspections, we can also help you understand the difference between the inspections so you can schedule the appropriate service.
Can You Get a 4-Point and Wind Mitigation Inspection at the Same Time?
Yes, and if you need both reports, scheduling them together is often the simplest option.
There is some overlap in the areas the inspector needs to access, particularly the roof and attic. However, the inspector is gathering different information for each report.
For the 4-Point Inspection, the roof is being evaluated as one of the home's four major systems.
For the Wind Mitigation Inspection, the inspector is documenting specific wind-resistant construction features, including details that may not be relevant to the 4-Point report.
Completing both during the same appointment can save you from scheduling two separate visits and gives you both sets of documentation to provide to your insurance agent.
This is particularly helpful for Pensacola and Northwest Florida homeowners who are purchasing an older home, changing insurance companies, or trying to get their insurance documentation updated.
Which Insurance Inspection Should You Schedule?
If your insurance company or agent has specifically requested a 4-Point Inspection, schedule the 4-Point.
If they're asking for a Wind Mitigation Inspection or you want your home's wind-resistant features documented for potential insurance credits, schedule the Wind Mitigation.
If they've requested both, the two inspections can typically be completed during the same visit.
And if you're still unsure, don't guess.
Insurance requirements can vary by carrier and property, and scheduling the wrong inspection only creates another step in the process.
Taylor-Made Home Inspections provides 4-Point and Wind Mitigation Inspections throughout Pensacola and Northwest Florida, with insurance-focused reports designed to give you and your insurance agent the documentation you need.
Whether you're buying a home, changing insurance companies, replacing your roof, or simply trying to make sure your current insurance documentation reflects the improvements you've made, we can help you determine which inspection makes sense for your situation.
Need a 4-Point Inspection, Wind Mitigation Inspection, or both?
Call Taylor-Made Home Inspections at 850-572-5531 to schedule your inspection in Pensacola or the surrounding Northwest Florida area.